
Think of your mortgage term like picking a pair of jeans. Two-year fix is a skinny jean—snug, trendy, but could stretch out quickly if interest rates change.
A ten-year fix is like a pair of elastic-waist sweatpants. Super comfy, but you’ll pay a bit more upfront for that cushion, and you might feel trapped if you want to move house.
The sweet spot? For most people, a five-year fixed rate is the Goldilocks choice. It’s not too risky, not too stiff, and it gives your monthly budget a nice, long hug.
But what if rates go down?
Ah, the big fear. You lock in a rate, and then the Bank of England (or your local central bank) drops rates like a hot potato. Suddenly, your neighbour is bragging about their lower variable rate.
Here’s the truth: you can’t time the market. Trust me, I tried to time buying avocados once, and I ended up with brown mush. Don’t be like me.
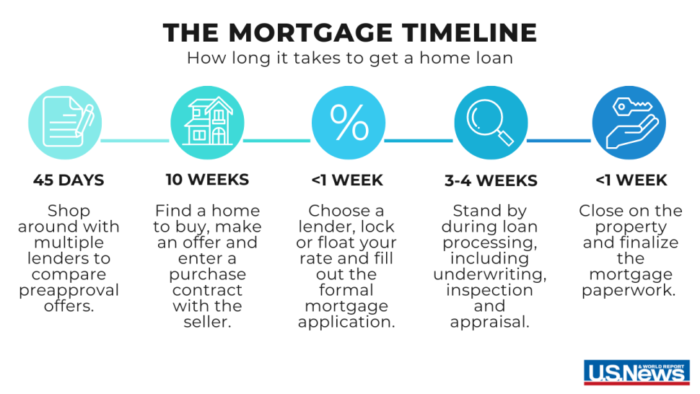 Complete Timeline of the Mortgage Process – Clarence Oliveira, REALTOR
Fixing gives you peace of mind. And peace of mind is worth more than the few hundred quid you might save chasing a lower rate. If rates do go down, you can always remortgage after your fix ends.
The “emergency fund” rule
Here’s a rule I made up, but it works: Fix as long as you can afford to pay the monthly bill without crying.
If you have a stable job and a little savings buffer, a short fix (two to three years) is fine. You can ride the waves like a surfer who knows how to swim.
But if your job is a bit wobbly, or if the thought of a rate hike keeps you up at night, go for a longer fix. It’s like buying a sturdy umbrella instead of a paper one—you’ll be dry even in a downpour.

