Here’s the psychological catch. You’re trading asset for liability. Your house is a “good” thing, and debt is a “bad” thing. Swapping one for the other feels like downgrading. But your house is illiquid—you can’t live on equity. Debt, meanwhile, is eating your income alive.
Imagine you owe $15k on a credit card at 22% interest. That’s costing you roughly $275 a month in finance charges. If you use $15k of your home equity to nuke that card, you’ve just given yourself a $275 monthly raise. That’s a pay bump without asking your boss. Pretty sweet, huh?
The trick is timing. You do this simultaneously with the sale. Your real estate attorney or closing agent can literally wire that chunk of cash directly to your credit card company before you ever see it. That way you’re not tempted to “treat yourself” to a vacation because the money disappeared into debt heaven.
But Wait—What About Your Next House?
I know what you’re thinking: “But I need that equity for my down payment on my next place!” Fair point. But here’s where you get clever. You don’t have to drain all of it. You can use, say, 50% to kill debt and 50% for the new house. It’s a balance, not an all-or-nothing game.
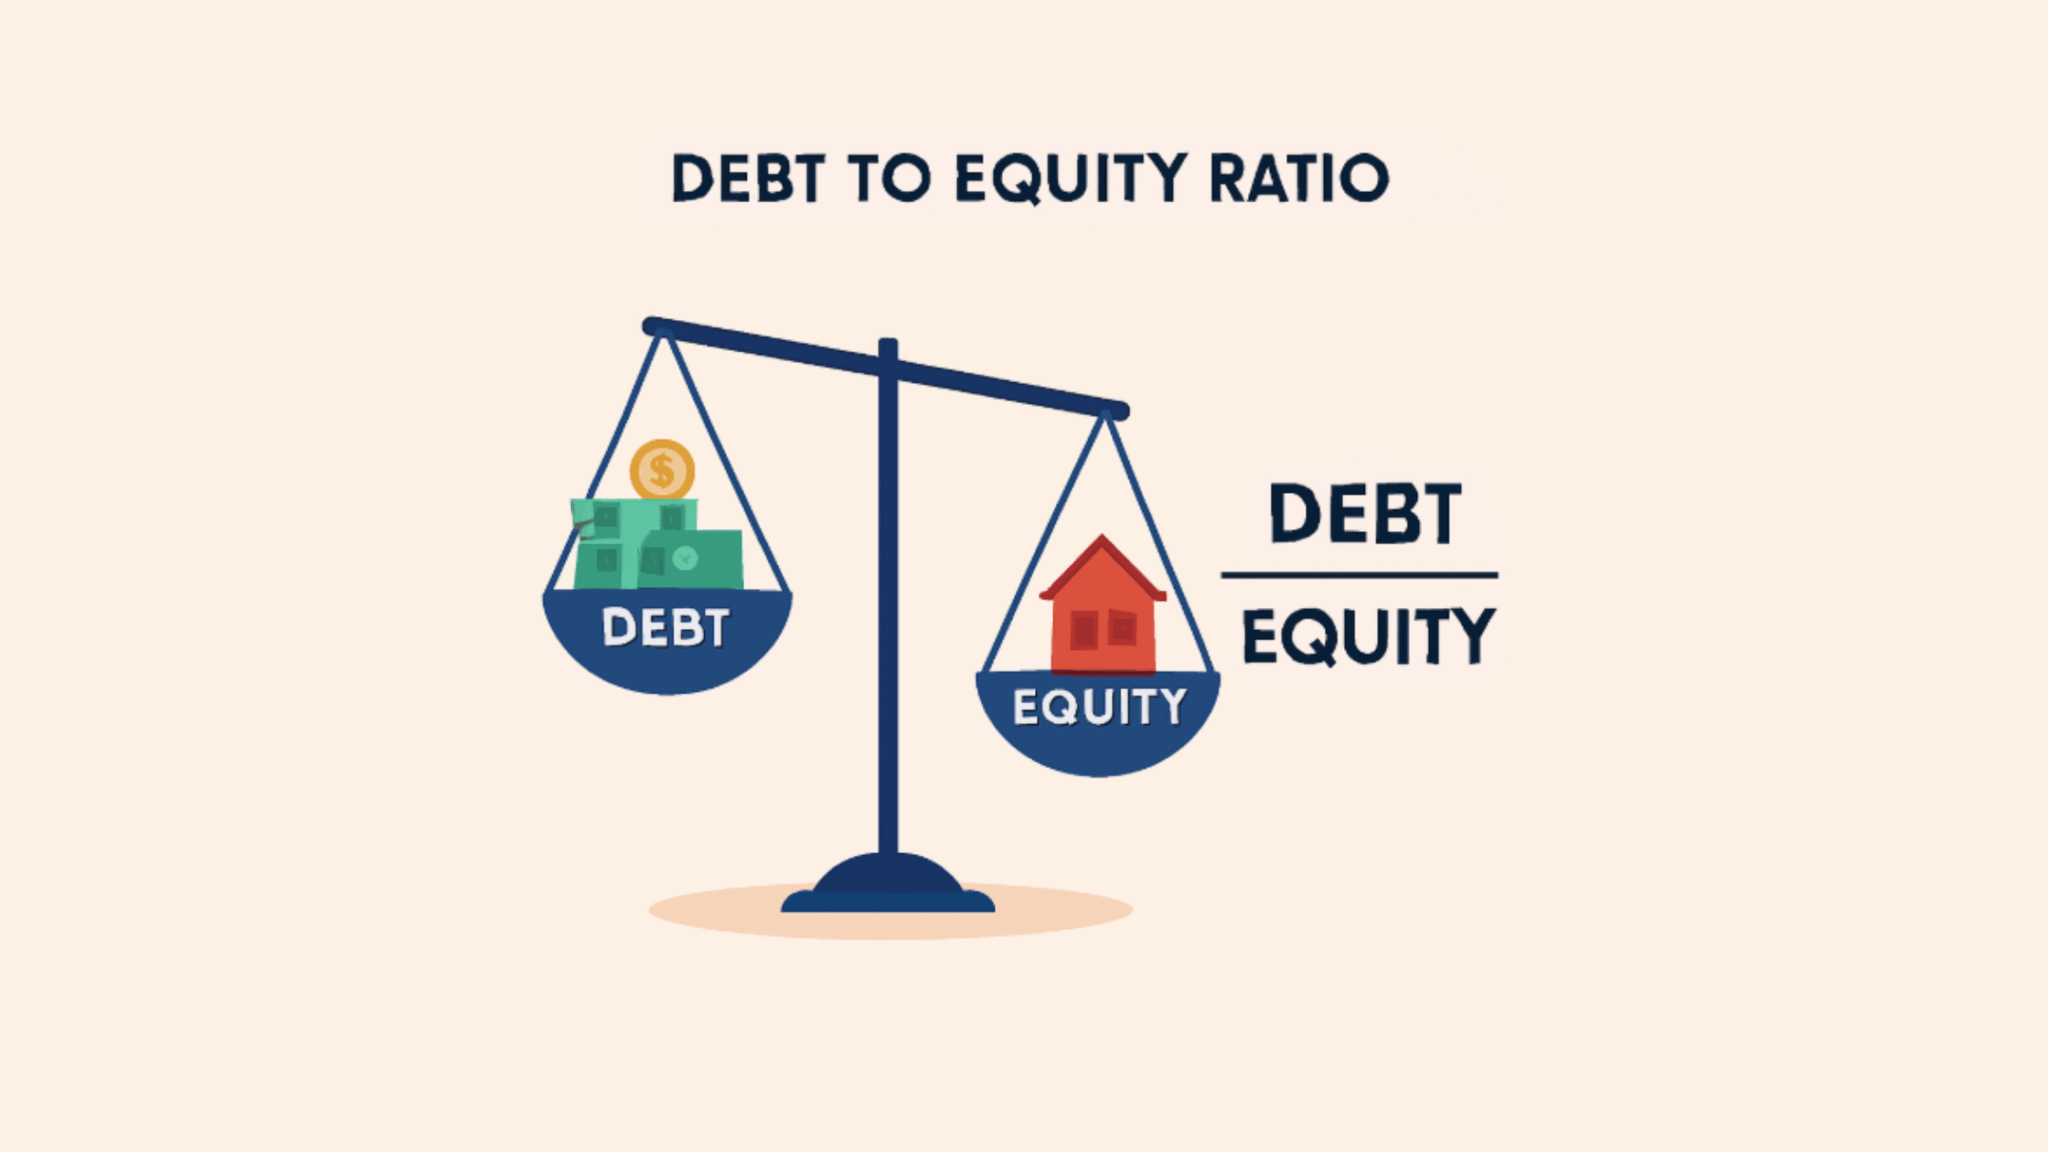 Debt to Equity Ratio Meaning, Formula & Examples | Ultima Markets
Or—and this is punk-rock—you could downsize. Yes, I said it. Move to a slightly smaller house or a different neighborhood. That frees up even more equity to blast away debt. You get a simpler life with fewer monthly payments. Your future self will send you a thank-you note.
Dave did exactly that. He used $8k of his equity to pay off his credit card, and the rest went into a modest down payment on a duplex. Now his mortgage is lower, his debt is zero, and he’s not waking up at 3 AM sweating about interest rates. He’s actually boring now. Boring is beautiful.

