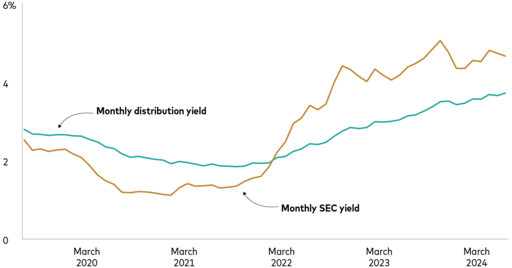
Here’s the bad news: distribution yield is a backward-looking metric. It’s like checking your rearview mirror while driving toward a cliff. It tells you what happened, not what’s coming. SEC yield is forward-looking (or at least less backward-looking). It assumes the last 30 days of income will continue for a year. Not perfect, but about as reliable as a weather forecast for tomorrow, not last week.
But wait—there’s a plot twist. SEC yield can also be misleading if you’re looking at funds with weird fee structures or exotic holdings. For example, a high-yield bond fund might have a sexy SEC yield, but if interest rates spike, the fund’s value will drop faster than a hot potato at a cooking show. Distribution yield will make you feel warm and fuzzy until you look at your account balance and cry into your coffee.
The Practical Get-Out-of-Jail-Free Card
So, what do you actually do with this info? First, if you’re buying a bond fund or a REIT, always check the SEC yield first. It’s the neutral, no-nonsense baseline. Then compare it to the distribution yield. If the distribution yield is significantly higher, ask yourself: “Am I getting paid from actual profits, or is this fund slowly eating itself?” The answer determines if you’ll be sipping Champagne or eating ramen next year.
 Total Bond: 23 years of SEC yield and distribution yield - Bogleheads.org
Here’s a surprising fact that’ll make you the star of your next Zoom call: Money market funds often have the two yields almost identical, because they’re legally required to be boring. That’s right—the most boring investments are the most honest. Meanwhile, some aggressive closed-end funds can have a distribution yield of 12% and an SEC yield of 3%, which is basically financial clickbait.

